
Watch JB's latest NZ property market update below, or keep scrolling to read the full article:
In a nutshell:
- Our latest GDP figures came in slightly positive at 0.2%—but the recovery’s still landing pretty unevenly. The lower South Island is booming, while elsewhere (Auckland and Wellington in particular) it’s taking longer to work through.
- In response to that improved growth, the market’s now pricing in two 0.25% OCR increases before Christmas. In our view, one more—just to get us back to a ‘neutral’ OCR of 3.00%—should do the trick.
- Fixed mortgage rates are expected to track up over the next couple of weeks in response to spiking wholesale rates, meaning borrowers who are heading for a refix soon would be advised to lock in sooner rather than later.
- The mixed bag we’re seeing across different parts of the economy is being echoed in the housing market—Auckland and Wellington remain soft, Canterbury (while still moving) is slowing, and parts of the lower South Island remain really strong.
- House prices aren’t expected to take off again as the economy gains momentum, but we should start to see something of a recovery over the next few months.
I feel like I’ve been repeating myself these last few updates, but—even though it doesn’t really feel like it yet—things are genuinely looking up out there.
Here’s the latest on what’s been happening across the New Zealand economy, property market and with the OCR and interest rates.
What’s been happening in the economy?
By the numbers, we’ve now officially edged into positive territory. Just.
Our latest GDP figures (for the June 2026 quarter) came in at 0.2%— the midpoint of the market’s forecasted range—with that growth largely down to the strength of our agri sector.
On the ground, the experience varies pretty wildly depending on where in New Zealand you’re talking about. Different parts of the country are like different planets right now.
In the lower South Island, there’s probably a sense of “hold on…what recession?”.
Canterbury’s economy is really strong at the moment, thanks to stimulus from the post-earthquake rebuild. That level of cash injection inevitably builds momentum—and growth builds on growth.
It’s the same in Otago and Southland, albeit for different reasons. Down there, the strength of the agri sector—meat and dairy both performing well—is flowing through to the wider region. They’ve also got a couple of big infrastructure projects in the works (a multi-billion dollar data centre in Southland, and, controversially, talks of a new goldmine in Tarras) helping to drive confidence and employment.
The rural North Island is faring well, again driven by the strength of the agri sector—but it’s another story in our major centres.
Wellington had such a massive peak in the last boom—fuelled by low interest rates, and a Labour government (meaning lots of work and decent pay)—that it had a long way to fall. It’s struggled over the last few years, and with the added uncertainty of this year’s election in the mix, that’s likely to continue for a while yet.
Auckland, too, is still waiting to for the trickle-down effect from the rural economy to land, but it’ll happen eventually.
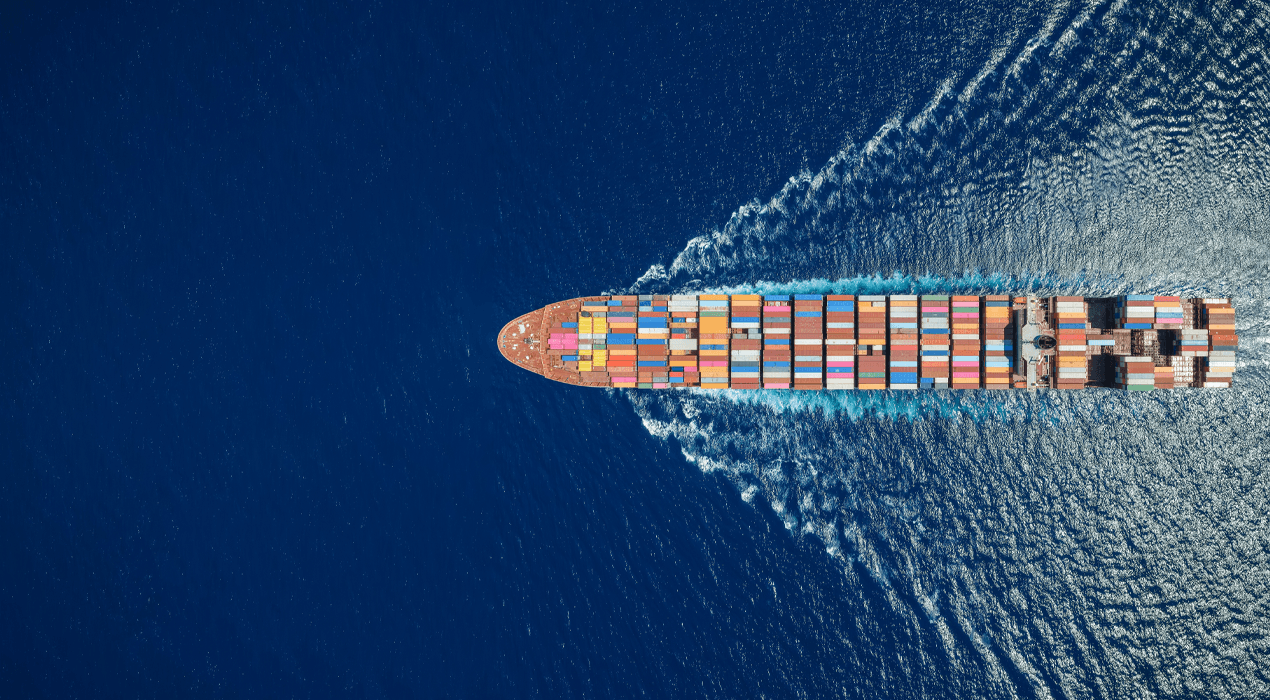
Economies are a bit like super-tankers. Once they’ve got momentum, it’s hard to lose. But equally, once they’ve stalled, it takes a long time to get the momentum back again.
It’s been a long, hard three or four years—and I actually think the glimmers of hope we’ve had along the way (“things are definitely getting better… oop, never mind.”) have made them feel that much harder.
While it’s not necessarily reflected in consumer confidence numbers yet—especially if you zone in on Auckland and Wellington—I’m firmly of the view that we are starting to come out the other side.
What will be the drivers of that wider economic recovery?
A few things are lining up.
There’s not too much evidence of it yet, but strong farm gate prices will continue to flow through from the regions into the cities—and once we’re out the other side of election uncertainty, that should flow through to the usual uptick in consumer and business confidence.
Probably the biggest factor heading into next year, though, is our massive pipeline of shovel-ready infrastructure projects—the Southland data centre being one, as well as the new Precinct Properties’ development in downtown Auckland, and several large roading projects.
New Zealand is small enough that it won’t take much to soak up spare capacity in the construction sector, so we could very quickly end up with labour shortages—and it’ll flow through to a degree of construction cost inflation as well.
What’s kind of interesting, though, is what’s happening across the Tasman.
Australia’s managed to avoid the sort of deep recession we’ve had here (it didn’t go as hard on interest rate hikes) but its economy has started to slow. House prices in Sydney and Melbourne have been falling in recent months, and it’s starting to flow through to other major centres (Adelaide, Brisbane and Perth) as well.
That should be good for us in that it’ll mean The Lucky Country won’t have quite the same pull it has in recent years—as evidenced by the tens of thousands of Kiwi that have jumped the ditch in search of greener pastures.
And it’ll also be a positive for our collective psychology. We won’t be looking at our neighbours with quite as much envy.
What's happening with the OCR and interest rates?
Our most recent Official Cash Rate (OCR) announcement on 2 September brought another 0.25% increase, to 2.75%.
Based on the Reserve Bank’s (RBNZ) current forecasts, we’re likely to get one more hike this year, before hanging out at 3.00% (i.e. ‘neutral’) for most of 2027. And in my mind, there’s not much evidence to suggest that we need to go beyond that.
The markets disagree, unfortunately.
Swap rates have tracked up by about quarter of a percent in recent days—in response to growing signs of life in the economy and offshore inflation pressures—now pricing in two further OCR increases before Christmas.
That movement is expected to flow through to mortgage rates over the next week or two, in terms of small increases across some of those shorter-term rates. For borrowers coming up to a refix soon, that means it’s probably worth locking in sooner rather than later.
Finally, how are things going across NZ’s property market?
That regional economic divide we’re seeing is also being reflected in the housing market.
Overall, the lower South Island remains strong and confident. Central Otago and Queenstown Lakes in particular are off the charts.
Canterbury’s housing market is cooling ever so slightly from the golden run it’s had in recent months, as the price advantage it had over our other major centres has narrowed. Properties are still selling, just not as quickly, and two-bedroom townhouses in particular are taking a while to shift—the massive amount of new-build activity going on down there has led to an oversupply problem, just like what we’ve got in Auckland.
Wellington’s still soft, and that’s not likely to change before we’re out the other side of the election.
Auckland’s pretty subdued—but there’s the feeling of maybe a mild recovery starting to show, as spring brings the usual lift in buyer activity. Oversupply’s been the main drag, with developers forced to drop prices in order to shift excess stock. That will start to be absorbed though as supply and demand come back into balance.
We’ve been saying for a while that it’s a golden opportunity for buyers, and there’s some great value to be had out there right now, particularly for anyone looking to get on the property ladder in Auckland.
Right now, we’re seeing brand new, well-designed, two-bed / two-bath townhouses (with garages) on the North Shore selling in the high $600s. That’s less than what you would have paid for something of lower quality three years ago, and roughly equivalent to what you would have paid 10 years ago.
Considering inflation has tracked at more than 30% over the last decade, that means prices have barely moved at all in inflation-adjusted terms.
Quality’s up, prices are down, and there’s plenty of stock selling below the actual cost to build.
We should start to see a bit more life return to the housing market over the coming months. But with all the policy changes government has delivered to help keep a lid on house prices, they’re unlikely to take off again in a hurry.
About the author: John Bolton (JB), Squirrel Founder & Group Head of Property Finance