
“Tonight New Zealand has spoken. It may take us a little bit longer to figure out what exactly it is that you’ve said.”
There’s been a lot going on since my last update—and the year’s not done yet.
I’ll do my best to unpack everything, but as usual, let’s start with a look at the Wellington property market by the numbers for September:
- It’s taking an average of 52 days to sell – which has finally come back a bit, so possibly a sign that inventory levels are reducing. The 10-year average for a September month is 40 days, so still some work to do.
- The above dovetails into the sales count, which is up 9.1% on August 2026. Possibly a bit of a flurry prior to the usual pause that comes in the lead up to an election.
- Median sales price us up close to 5% on a month to month basis, however down 2% compared to the same time last year.
One headline grabbing a bit of attention has been Wellington City Council’s consultation on council rates.
Commercial landlords have been fairly vocal campaigning against this, as it will seemingly destroy what’s left of the retail / hospitality scene.
Intentions are good in that it will hopefully discourage land-banking, but it seems like it will create a lot of collateral damage. I doubt it’ll get past consultation, but could be favourable for some homeowners, depending on land holding.
So what else has been going on? Let's start with the Official Cash Rate.
We got a hold decision from the Reserve Bank on 28 October, and I wasn’t surprised.
The financial markets were at 95% chance of an increase the night before, and to be fair the vote was split 4 to 3, so it was a close thing. But I still stuck to my guns.
I think a pause now was appropriate to get us through the election (more on that shortly), but the Reserve Bank’s core mandate is to keep inflation under control.
And while the data for the September quarter showed things tracking in the right direction—down to 3.7% from 4.1% in the June quarter—I do believe that we are still in an inflationary environment.
So, we probably won’t be as lucky at our next OCR announcement in December.
I listened to a decent podcast recently, which talked about the idea that the Middle East (and petrol cost inflation) is a bit of a smoke screen for true inflation, which is being driven by technology.
We used to get more bang for buck in processing power, but nowadays we’re always paying more for phones and tech with a smaller reciprocal increase.
And let’s face it – everything has tech in it now. Take me back to the days when a car / washing machine / dryer didn’t need Wi-Fi…. Yes, boomer….
The podcast also recommended de-regulation as the path forward, similar to the US – take from that what you will, but there’s been a change over there recently hasn’t there?
A quick look across the ditch
In a welcome change, Australia now seems to be beating us in home loan rates, and Reserve Bank interest rates – now sitting at 4.85%, with inflation figures running at 4.3% in September.
Our Australian counterparts generally see a more immediate impact when increasing interest rates, as the majority of their mortgage loans are on floating—it doesn’t seem to have had the desired impact thus far though.
We went hard early, however, and now we’re in a bit of a recalibration phase, with external factors hampering our efforts.
What do the US mid-terms mean for us?
Well the Democrats took this one out convincingly.
So much so that DJT couldn’t even claim meddling / interference / fraud—yet. They don’t take their seats until January, so there could be a bit of action between now and then.
Other than that, we can expect to be in for a lot of back and forth, with Trump enacting measures, then getting them rolled back. Democrats trying to pass legislation, and it getting vetoed.
There may be some sacrifices of Trump’s team along the way, which will make for ‘mini-spectacles’, and good media fodder, but really that’s sideline fluff.
Somebody release the files already.
And now we’re back to the start of this article—our own general election.
We’ve spoken, but the outcome is still TBC. Likely a National coalition again by the sounds, which isn’t perfect for Wellington if I’m honest.
There was a bit of a battle cry when I was in the banks: “We need to win in Auckland – if we can’t do that, we’re not winning anywhere.” I get it, and for a foreign owned national company, I can understand that.
For a government? It’s a different story.
Time will tell, and I’m unsure if the opposition were going to have a more favourable impact, but the best option for NZ is to work through the impacts from offshore and stick to our knitting for the time being. Homegrown innovation and specialisation is the way, but good to have the agri sector to fall back on in tough times such as we are currently in.
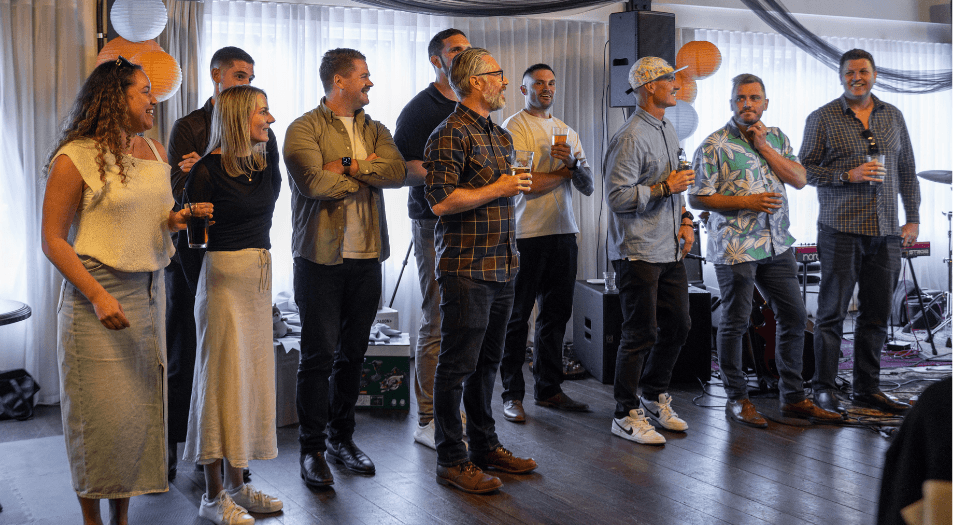
And to finish off, we just had our annual First Home Buyers Housewarming gig, where we invite back clients (and their friends) who purchased throughout the year!
Great day, and an absolute banger.
Until next time – roll on Christmas!
About the author: Nick Virtue, Squirrel Mortgage Adviser - Wellington
Nick cut his teeth inside the big banks—racking up 15 years' experience across SME, franchise, health and large corporate clients—before taking the leap to become a mortgage adviser in 2020. As one of our resident Wellington home loan experts, Nick knows the Capital (and its housing market) like the back of his hand. Whether working with clients or chatting to media, he has a way of breaking down the complex world of mortgages into simple, easy-to-understand language.